Penyusunan Laporan Keuangan UMKM Berdasarkan Standar Akuntansi Keuangan Entitas Mikro Kecil Menengah pada Usaha Kerupuk Spesial Tamban di Sei Lekop Kabupaten Bintan Preparation of Financial Statements for Micro, Small, and Medium Enterprises (MSMEs) Based on the Financial Accounting Standards for Micro, Small, and Medium Entities in the Kerupuk Spesial Tamban Business in Sei Lekop, Bintan Regency

Article Sidebar
 Page Numbers:
185-199
 Digital Object Identifier:


 Viewed: 195 times
 Downloaded: 132 times




LYAS Publisher cordially invites qualified professionals to serve as Editors or Reviewers. Your expertise will make an important contribution to maintaining and strengthening the academic quality of our publications. Interested applicants are kindly requested to complete the application form at the following link: Editors & Reviewers

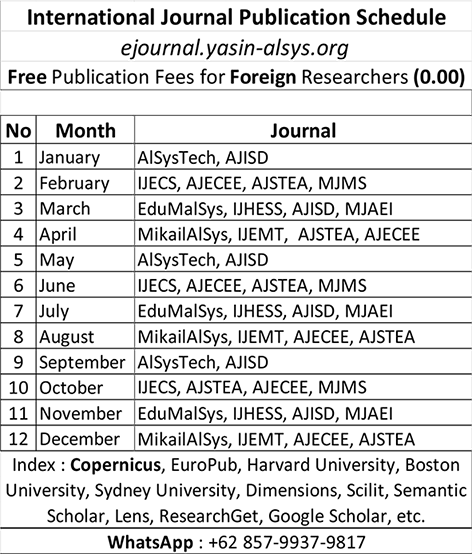
Please feel free to contact us if you need any further information about the submission process or if you have any additional questions.
 Authors:
Marshanda Marshanda1*, Mery Andayani2, Syaqilla Syaqilla3, Hadli Lidya Rikayana4
 Copyright :
Authors retain copyright and grant the journal right of first publication.
Main Article Content
Abstract
This study was motivated by the fact that many micro, small, and medium enterprises (MSMEs) have not yet prepared financial statements in accordance with applicable accounting standards due to limited knowledge and resources, as seen in the case of the Kerupuk Spesial Tamban business in Sei Lekop, Bintan Regency, which still uses simple bookkeeping that does not comply with the Financial Accounting Standards for Micro, Small, and Medium Entities (SAK EMKM). This study aimed to prepare financial statements for the Kerupuk Spesial Tamban business in accordance with SAK EMKM, identify shortcomings in the existing accounting system, and formulate recommendations to improve the quality of financial reporting in order to support business development. A descriptive qualitative approach was employed, with data collected through interviews, observation, and documentation related to production activities, costs, and financial transactions, which were subsequently analyzed through data reconciliation into the SAK EMKM format, including the statement of financial position, income statement, and notes to the financial statements. The findings show that the application of SAK EMKM produced more systematic, accurate, and informative financial statements, with a positive financial position indicated by assets exceeding liabilities and a significant net profit after adjustments. The preparation of SAK EMKM-based financial statements enhanced transparency and accountability, facilitated operational decision-making, and opened opportunities for access to financing, although full implementation remains constrained by limited human resources. The study concludes that the application of SAK EMKM contributes to improving the quality of financial reporting for MSMEs and recommends consistent daily bookkeeping and the strengthening of business owners’ accounting capacity to ensure business sustainability and growth.
Citation Metrics:
Downloads
Citation Metrics & Similar Scopus Articles
-
Heradhyaksa B. (2026)Cross-Jurisdictional Reporting Standards for Cash Waqf: A Comparative Normative Legal Study of Indonesia and MalaysiaEl Mashlahah, 16(1), 155-182
-
Pebrain M.R. (2026)The Impact of Digital Transformation on Economic Growth in Indonesia a Case Study of UMKM Juara and Creative Economy in Sukabumi CityAip Conference Proceedings, 3432(1)
-
Azizah I. (2026)Reconstructing Islamic Criminal Liability for Economic Crimes: A Maqāṣid-Based Framework for Indonesia’s Sharia FinanceEl Mashlahah, 16(1), 41-64
Article Details

Authors retain copyright and grant the journal right of first publication with the work simultaneously licensed under a Creative Commons Attribution-NonCommercial-ShareAlike 4.0 International License that allows others to share the work with an acknowledgement of the work's authorship and initial publication in this journal.
References
Afriansyah, B., Niarti, U., & Hermelinda, T. (2021). Analisis Implementasi Penyusunan Laporan Keuangan pada UMKM Berdasarkan Standar Akuntansi Keuangan Entitas Mikro, Kecil, dan Menengah (SAK EMKM). Jurnal Saintifik (Multi Science Journal), 19(1), 25–30. https://doi.org/10.58222/js.v19i1.99
Dipya, I. N. T., & Martadinata, I. P. H. (2024). Penentuan Harga Pokok Produksi dengan Metode Activity Based Costing Produk Minyak Kemiri Bakar pada UMKM Oemah Uncle B di Kabupaten Buleleng. Jurnal Ilmiah Akuntansi dan Humanika, 14(1), 43–54. https://ejournal.undiksha.ac.id/index.php/JJA/article/view/76637
Hasibuan, A. N. (2024). Analisis Biaya Standar sebagai Alat Perencanaan dan Pengendalian Biaya Produksi pada UMKM. Jurnal Bisnis dan Ekonomi, 2(1), 137–149. https://doi.org/10.61597/jbe-ogzrp.v2i1.24
IAI. (2018). Standar Akuntansi Keuangan Entitas Mikro, Kecil, dan Menengah. Ikatan Akuntan Indonesia.
Jazuli, A., Salsabila, A. Y., Assidiqi, A. H., & Sadiyah, D. (2023). The strategy of the head of madrasah in cultivating Fastabiqul Khoirot culture in the state high school environment in Batu City. EDHJ Unnusa, 8(April), 56–65. https://journal2.unusa.ac.id/index.php/EHDJ/article/view/4849
Mulyana, A. E. (2023). Peningkatan Kinerja UMKM Bidang Manufaktur melalui Pendampingan dan Edukasi Pengelolaan Persediaan Bahan Baku. DISTIRA-Jurnal Pengabdian Inovasi dan Teknologi Kepada Masyarakat, 3(1), 85–97. https://doi.org/10.58794/jdt.v3i1.442
Oktaviranti, A., & Alamsyah, M. I. (2023). Literasi Keuangan, Persepsi UMKM terhadap Kualitas Laporan Keuangan dengan Penerapan SAK EMKM. Jurnal Penelitian Ekonomi Akuntansi (JENSI), 7(1), 133–143. https://doi.org/10.33059/jensi.v7i1.7659
Ratih, A. E., & Rikayana, H. L. (2022). Perhitungan Harga Pokok Produksi Produk UMKM Kube Kencana 3 di Desa Sungai Lekop Kabupaten Bintan. Journal of Maritime Empowerment, 4(2), 55–59. https://ojs.umrah.ac.id/index.php/jme
Tatik. (2018). Implementasi SAK EMKM (Standar Akuntansi Keuangan Entitas Mikro Kecil dan Menengah) pada Laporan Keuangan UMKM (Studi Kasus pada UMKM XYZ Yogyakarta). Relasi: Jurnal Ekonomi, 14(2), 1–14. https://doi.org/10.31967/relasi.v14i2.260
Utari, R., Harahap, I., & Syahbudi, M. (2022). Penerapan SAK EMKM pada Usaha Mikro, Kecil, dan Menengah: Studi Kasus UMKM di Kota Tanjungbalai. Jurnal Ilmiah Akuntansi Kesatuan, 10(3), 491–498. https://doi.org/10.37641/jiakes.v10i3.1449
Wardani, F. K., & Wardana, B. E. (2022). Prinsip Dasar dan Konsep Dasar Akuntansi. Asian Journal of Management Analytics, 1(2), 125–136. https://journal.formosapublisher.org/index.php/ajma
Wicaksono, G., Kusumaningtyas Priyambodo, V., Sukma, P., Parju, N., Ridhawati, R., Hanani, T., Rizki, N., Fauzan, R., Anggun Hilendri Lestari, B., T., C. I. T. P., & Satriana, E. D. (2023). Akuntansi Perusahaan Manufaktur. https://play.google.com/books/reader?id=c3atEAAAQBAJ
Widad, N. F. Al, & Nawangsari, A. T. (2025). Implementasi Akuntabilitas Pelaporan Keuangan sebagai Upaya Peningkatan Transparansi dan Kepercayaan Publik pada PT Bank Jatim. Scientific Journal of Reflection: Economic, Accounting, Management, & Business, 8(4), 309–321. https://doi.org/10.37481/sjr.v8i4.1292
Widati, S., Yulianti, V., Wulandari, D. S., & Pratama, A. D. (2025). Pemberdayaan UMKM melalui Literasi Akuntansi dan Pajak untuk Penguatan Legalitas Usaha. Lentera Pengabdian, 3(2), 126–135. https://doi.org/10.59422/lp.v3i02.863
Yolanda, C. (2024). Peran Usaha Mikro, Kecil dan Menengah (UMKM) dalam Pengembangan Ekonomi Indonesia. Jurnal Manajemen dan Bisnis, 2(3), 170–186. https://doi.org/10.36490/jmdb.v2i3.1147